• Skip to primary navigation
  • Skip to main content

The One Percent Almanack

Wit and Wisdom on Investing, Business, and Life

  • Home
  • Members
  • Log In|Log Out
  • Show Search
Hide Search

Special Report

Life 2.0: In Reading, Choose Depth Over Breadth

December 30, 2016

Seneca was a Roman Stoic philosopher who lived during 4 BC – AD 65. He was a tutor and later advisor to emperor Nero, and was forced to commit suicide for alleged involvement in the conspiracy to assassinate Nero (though some sources state that he may have been innocent).

During the last two years of his life, Seneca spent his time in travelling, composing essays on natural history and incorrespondence with his friend Lucilius. In these letters, 124 of which are available, he covered a wide variety of topics, including true and false friendship, sharing knowledge, old age, retirement, and death.

Here is what Seneca wrote in his second letter to Lucilius – On Discursiveness in Reading – which I am posting as it is here, and which contains the answer to the dilemma most of us face on what to read as investors (by the way, ‘discursiveness’ means moving from topic to topic without order) –

Over to Seneca.

On Discursiveness in Reading
Seneca wrote to Lucilius –

The primary indication, to my thinking, of a well-ordered mind is a man’s ability to remain in one place and linger in his own company.

<!–more–>[show_to accesslevel=’almanack-all’]

Be careful, however, lest this reading of many authors and books of every sort may tend to make you discursive and unsteady. You must linger among a limited number of master thinkers, and digest their works, if you would derive ideas which shall win firm hold in your mind. Everywhere means nowhere.

When a person spends all his time in foreign travel, he ends by having many acquaintances, but no friends. And the same thing must hold true of men who seek intimate acquaintance with no single author, but visit them all in a hasty and hurried manner.

Food does no good and is not assimilated into the body if it leaves the stomach as soon as it is eaten; nothing hinders a cure so much as frequent change of medicine; no wound will heal when one salve is tried after another; a plant which is often moved can never grow strong. There is nothing so efficacious that it can be helpful while it is being shifted about. And in reading of many books is distraction.

Accordingly, since you cannot read all the books which you may possess, it is enough to possess only as many books as you can read.

“But,” you reply, “I wish to dip first into one book and then into another.” I tell you that it is the sign of an overnice appetite to toy with many dishes; for when they are manifold and varied, they cloy but do not nourish. So you should always read standard authors; and when you crave a change, fall back upon those whom you read before. Each day acquire something that will fortify you against poverty, against death, indeed against other misfortunes as well; and after you have run over many thoughts, select one to be thoroughly digested that day.

This is my own custom; from the many things which I have read, I claim some one part for myself.

At the end of this very letter, Seneca also shared his thoughts on the limits of one’s wealth. He wrote –

Epicurus says: “Contented poverty is an honourable estate.” Indeed, if it be contented, it is not poverty at all. It is not the man who has too little, but the man who craves more, that is poor. What does it matter how much a man has laid up in his safe, or in his warehouse, how large are his flocks and how fat his dividends, if he covets his neighbour’s property, and reckons, not his past gains, but his hopes of gains to come?

Do you ask what is the proper limit to wealth? It is, first, to have what is necessary, and, second, to have what is enough.

From Seneca to Sherlock
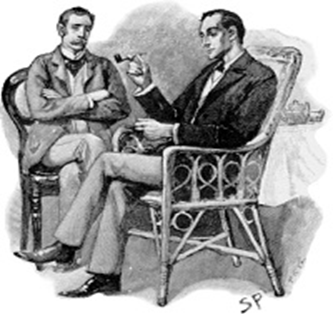

As I was reading Seneca’s letter, I was reminded of what Sherlock Holmes told his accomplice Watson in A Study in Scarlet –

I consider that a man’s brain originally is like a little empty attic, and you have to stock it with such furniture as you choose. A fool takes in all the lumber of every sort that he comes across, so that the knowledge which might be useful to him gets crowded out, or at best is jumbled up with a lot of other things so that he has a difficulty in laying his hands upon it.

Holmes added…

Now the skillful workman is very careful indeed as to what he takes into his brain-attic. he will have nothing but the tools which may help him in doing his work, but of these he has a large assortment, and all in the most perfect order. It is a mistake to think that that little room has elastic walls and can distend to any extent. Depend upon it there comes a time when for every addition of knowledge you forget something that you knew before. It is of the highest importance, therefore, not to have useless facts elbowing out the useful ones.

As years have passed, I have turned from trying my hands at speed reading – acting like Holmes’ fool who takes in all the lumber of every sort that he comes across – to slow, thoughtful reading and re-reading. Slow reading, as a wise man said, is not so much about unleashing the reader’s creativity, as uncovering the author’s.

Often, it’s the same old books – the supertexts – that I refer to again and again…for each time I go through them, I get a few new and brilliant insights that missed my eyes in the previous readings.

Don’t Read…Reread

Vladimir Nabokov, the author of Lolita tells us –

Curiously enough, one cannot read a book: one can only reread it.

When we read a book for the first time, the very process of laboriously moving our eyes from left to right, line after line, page after page, this complicated physical work upon the book, the very process of learning in terms of space and time what the book is about, this stands between us and artistic appreciation.

Only on a third or fourth reading do we start behaving toward a book as we would toward a painting, holding it all in the mind at once.

To bring back Seneca and what he wrote to Lucilius –

Be careful, however, lest this reading of many authors and books of every sort may tend to make you discursive and unsteady. You must linger among a limited number of master thinkers, and digest their works, if you would derive ideas which shall win firm hold in your mind. Everywhere means nowhere.

While it’s a good idea to read stuff across domains and authors, if you are unsure of what to start and where to focus your intellectual capacities on, consider the super-texts. Read them once, and then read them again…and again…and you will do just fine. The idea is to not be in perpetual locomotion and jump from one book or author to another. The idea is to sit back, contemplate, and relate the facts you read to each other. But start reading if you haven’t already, or you would miss out on the huge compounding benefits of the same as years pass.

[/show_to] [hide_from accesslevel=’almanack-all’]

Want to Read More? This content is exclusive for members of Value Investing Almanack. Login to read if you are a member. Else, click here to subscribe.

Benefits to VIA Members
 
  • Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
  • InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
  • StockTalk: Thorough analysis of business models of companies (without any recommendations)
  • Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
  • BookWorm: Reviews of the best books on Value Investing and related subjects
  • Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
  • Archives: Instant access to our huge archive from the past three years
Become a VIA Member. Click to Subscribe
[/hide_from]

Super Investor: Seth Klarman on Perils of Top-Down Investing

December 30, 2016

Reading the super texts i.e., words written by legendary thinkers, investor and philosophers is something that one can never get enough of. These texts are so deep and pack such a concentrated dose of wisdom that the only way to benefit from them is to read them again and again. It’s like a giant onion with densely squeezed layers. When you’ve peeled one layer, then and only then, the juicier layer makes itself available.

Seth Klarman is one such super investor and his book Margin of Safety is that super text which needs to be read every year (at least). And every time I read it, I discover a fresh insight and wonder how I missed it during my last read. It happens because once I get a grip on one idea, it increases (slightly) my mind’s ability to receive another idea. And bit by bit, over a period, brain muscles become stronger to imbibe the deeper wisdom.

I would go as far as saying this – if an investor hasn’t read a super text multiple times, he’s as uninformed as the guy who hasn’t read it at all. Warren Buffett’s letters, Benjamin Graham’s The Intelligent Investor, Poor Charlie’s Almanack are some super texts that demand revision multiple times.

<!–more–>[show_to accesslevel=’almanack-all’]

Anyways, coming back to Margin of Safety, I was re-reading Chapter 7 titled “At the Root of a Value-Investment Philosophy” in which Klarman writes –

There are three central elements to a value-investment philosophy. First, value investing is a bottom-up strategy entailing the identification of specific undervalued investment opportunities. Second, value investing is absolute-performance, not relative-performance oriented. Finally, value investing is a risk-averse approach; attention is paid as much to what can go wrong (risk) as to what can go right (return).

In the subsequent pages, Klarman elaborates on the perils of top-down investing and how a bottom-up approach is a much more sensible strategy for a small investor. This is the section where I stumbled upon few remarkable insights which hadn’t broken through my wall of ignorance during previous readings. So, before I start listing those merits and demerits, let’s come to an agreement on the definition of bottom-up investing and what one means by top-down investing.

Top-down investing refers to the process where the investment ideas originate from macroeconomic events like a change in economic policy or an emergence of a new trend in a country or world’s economy. In the Indian context, few examples of such events include the recent decision of demonetization or a political party coming to power with an overwhelming majority. In the global context, it could be events such as the result of US presidential election or Brexit or political unrest in some countries.

In bottom-up investing, no importance is given to macroeconomic changes. The focus is on sifting through the businesses, one by one, and identifying individual investment opportunities. Bottom-up investors search for bargains business by business, analyzing each case on its own merits.

Top-Down is Highly Error Prone

The primary problem with top-down is that it requires an investor to predict the future accurately and then decide based on those predictions. Klarman writes –

“This approach is difficult and risky, being vulnerable to error at every step. Practitioners need to accurately forecast macroeconomic conditions and then correctly interpret their impact on various sectors of the overall economy, on particular industries, and finally on pecific companies.

Take the case of demonetization. When the news came out, many investors (including yours truly) started speculating about which sectors and industries will be affected (positively or negatively) because of this unexpected shock. I figured that NBFC is one industry which is heavily dependent on cash transactions so it’s a good candidate to get hit. Then I further speculated that commercial vehicle finance companies are the ones which will get adversely affected. Should I buy debt funds that own bonds of those companies? Should I directly buy the stocks of such companies? Will the companies recover from this temporary trouble and come out unscathed? Assuming the probability of my assumption being correct in each step is an optimistic 75 percent (which is a hugely overconfident assumption), getting it right finally amounts to 0.75 x 0.75 x 0.75 x 0.75 (four assumptions) i.e., 31 percent. Should I bet my hard-earned money on such a low probability event?

Let’s say that an investor manages to get all the above steps right, the issue is that market inefficiencies emanating from such macroeconomic events are extremely short lived. Seth argues –

It is also essential for top-down investors to perform this exercise quickly as well as accurately, or others may get there first and, through their buying or selling, cause prices to reflect the forecast macroeconomic developments, thereby eliminating the profit potential for latecomers…The top-down investor thus faces the daunting task of predicting the unpredictable more accurately and faster than thousands of other bright people, all of them trying to do the same thing.

Which means top-down investors are always in a hurry to act on their insights. I don’t need to convince you that any decision taken in haste is highly error prone and has very high odds to lead to future troubles. This forced urgency is an unavoidable problem in the top-down approach.

Bottom-up investing is much simpler thus less prone to error. While a top-down investor must make several accurate predictions in a row, writes Klarman, “a bottom-up investor is not in the forecasting business at all.” In fact, non-predictive decision making is a very important mental model and bottom-up investing is its clearest example. In the stock market, randomness, unpredictability, and incomplete information aren’t exceptions but a norm.

Top-Down is a Game of Expectations

Top-down investing is driven by themes or trends and top-down investors are always on the hunt for catching a big wave. They act like surfers who stand up on their surfing board whenever they anticipate an oncoming wave. Since there’s no foolproof way to predict a big wave, top-down investors get burned out by trying to get on to every little wiggle in the sea called the stock market. Moreover, it’s important to get the direction of the way right else you not only miss the wave but run the risk of getting drowned in the same wave. Klarman warns –

Another difficulty with a top-down approach is gauging the level of expectations already reflected in a company’s current share price. If you expect a business to grow 10 percent a year based on your top-down forecast and buy its stock betting on that growth, you could lose money if the market price reflects investor expectations of 15 percent growth but a lower rate is achieved. The expectations of others must therefore be considered as part of any top-down investment decision.

To exploit a trend, for most investors the focus invariably shifts from “what a business is going to do in the future” to “what would catch the fancy of other investors.” In other words, the whole idea of value goes out of the window and investing transforms into a game of guessing. When you buy a stock, believing others will soon be buying the same thing, you’re not investing. You’re speculating.

The only useful aspect of top-down view is when one is trying to assess the value of business. Among many other valuation methods, relative valuation is one where an investor tries to arrive at an estimate of a company by comparing it with other similar companies in the same industry. But that’s also done as means to challenge your own estimate and make one think harder. Other than this, the opinion of others doesn’t mean much to bottom-up investors.

The Cash Confusion

A lot of top-down investors hold cash to time the market which is again an error-prone approach and a slave to accurate predictions.

Bottom-up investors hold cash when they are unable to find attractive investment opportunities and put cash to work when such opportunities appear. A bottom-up investor chooses to be fully invested only when a diversified portfolio of attractive investments is available. Top-down investors, by contrast, may attempt to time the market, something bottom-up investors do not do. Market timing involves making a judgment about the overall market direction; when top-down investors believe the market will decline, they sell stocks to hold cash, awaiting a more bullish opinion.

John Maynard Keynes’ once warned – “The market can remain irrational longer than you can remain solvent.” His warning was for those who use leverage to time the market. I think Keynes’ advice can be extended for cash also. Remember, if you’re holding cash hoping for a crash, it may not come before your patience runs out.

If you permit me, I would like to modify the adage to – “The market can remain irrational longer than you can remain hopeful.” Don’t let the distant hope of a market crash stop you from investing in a great business.

The Difficult Sell Decision

A Japanese knight and a Korean warrior were in a vicious sword fight. After first few minutes, the knight makes a surprise move and swings his katana across the warrior’s face.

The Korean exclaims, “You missed!”

“Wait till you shake your head,” replies the knight.

The moral of the story is that sometimes it’s too late to realize that you made a mistake.

One of the reasons why an investor should sell a stock is when he or she realizes that his or her hypothesis is wrong or things have taken a bad turn. In other words, when you identify your mistake first thing you do is sell your position. If you don’t you’re just compounding the mistake and making it more severe. Klarman writes –

Top-down investors may find it difficult to know when their bet is no longer valid. If you invest based on a judgment that interest rates will decline but they rise instead, how and when do you decide that you were wrong?

Your bet may eventually prove correct, but then again it may not. Unlike judgments about value that can easily be reaffirmed, the possible grounds for reversing an investment decision that was made based upon a top-down prediction of the future are simply not clear.

Conclusion

As per Klarman, the heart of bottom-up investing is this –

The entire strategy can be concisely described as “buy a bargain and wait.” Investors must learn to assess value in order to know a bargain when they see one. Then they must exhibit the patience and discipline to wait a until a bargain emerges from their searches and buy it, regardless of the prevailing direction of the market or their own views about the economy at large.

Bottom-up investing may be a subset of value investing and lot of accomplished and wise value investors may not practice bottom-up investing all the time. However, if you are a small investor, then bottom-up investing is the safest and smartest option for you.

[/show_to] [hide_from accesslevel=’almanack-all’]

Want to Read More? This content is exclusive for members of Value Investing Almanack. Login to read if you are a member. Else, click here to subscribe.

Benefits to VIA Members
 
  • Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
  • InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
  • StockTalk: Thorough analysis of business models of companies (without any recommendations)
  • Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
  • BookWorm: Reviews of the best books on Value Investing and related subjects
  • Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
  • Archives: Instant access to our huge archive from the past three years
Become a VIA Member. Click to Subscribe
[/hide_from]

Life 2.0: Do You Have a Pink Shirt?

November 30, 2016

In my first year in college, Manish lived just two rooms next to me in the hostel. He was 6 feet 2 inches tall, very friendly and very smart. In the first semester, he scored 98.8 percent and was ranked second in the institute. It wasn’t a small feat considering that the institute was IIT Bombay.

I knew his work ethics and diligence in studies so his academic performance wasn’t a surprise. Getting up at 4 am for studying and attending all the classes regularly came naturally to him. Maybe he made it look that way. But there was one thing very unusual about him. On the day of the exam, he always used to wear his favourite pink shirt. People admired him for his intelligence, hard work, and focus but his superstition about pink shirt just didn’t make sense. It even earned him a nickname – Pinky.

Not to mention, there were few other, less irritating, peculiarities about him. For example, both his table-clock and his watch were set 15-minutes ahead of the actual time. He couldn’t tolerate seeing a footwear upside down. And he never missed his 30-minute afternoon nap, come what may.

<!–more–>[show_to accesslevel=’almanack-all’]

I once argued with him, “When you know your clock is 15 minutes ahead, you would work according to that. How does it help? In fact, every time you must mentally adjust the time and then work accordingly. It unnecessarily increases your cognitive load.”

He would brush me off, “It’s a hack and it works for me.” I just couldn’t wrap my head around his strange habits. He knew what he was doing, after all, he was the institute-topper and I barely managed to get passing marks.

One day, his wing mates, including me, decided to play a prank on him. This was February 2000, my second semester of college, and our mid-semester exams had just started. Manish’s routine on exam days was like a clockwork. Our exams would start at 2 pm so he would finish his lunch by 12.30 pm and head back to his room for a 30-minute nap. When he was asleep, we locked his room from outside, changed the time in his alarm clock (and his wristwatch) to 3 pm, turned his footwear upside down and hid his favourite pink shirt.

True to his biological clock, he got up after exactly 30 minutes of nap and found everything wrong. Upside down footwear, locked doors, missing pink shirt and of course the clock said he had overslept. He became agitated and started shouting frantically. That’s when we decided to end the prank and opened his doors. He wasn’t very pleased with our idea of having fun and quietly left for the exams, wearing a different shirt. He scored his 98 out of 100 in that paper.

The day exam results were declared, some of us told him, “See! Your pink shirt doesn’t have any special powers. It’s your superstition.”

“It’s not a superstition. But you guys won’t understand so forget it.” Manish replied. He continued to sport his pink shirt on exam days for the rest of his time in college.

I forgot about this incident until recently when I came across an interesting passage in Rafael Nadal’s autobiography where he describes his routine just before a match –

I sat down, took off my white tracksuit top, and took a sip from a bottle of water. Then from a second bottle. I repeat the sequence, every time, before a match begins, and at every break between games, until a match is over. A sip from one bottle, and then from another. And then I put the two bottles down at my feet, in front of my chair to my left, one neatly behind the other, diagonally aimed at the court. Some call it superstition, but it’s not. If it were superstition, why would I keep doing the same thing over and over whether I win or lose? It’s a way of placing myself in a match, ordering my surroundings to match the order I seek in my head.

So, Manish was right. His pink shirt wasn’t a superstition. It was a way for him to send a subconscious signal to his mind that it’s time to get ready for peak performance. Manish understood what top performing athletes know. It was an intelligent hack which, on the surface, looked like a stupid superstition. No wonder Manish passed engineering at the top of his class, secured a full scholarship from Stanford University for higher studies and bagged the most coveted job in the campus placement. He knew the secret.

Sharpening the mind’s focus on the activity at hand requires deep concentration. Peak performers know the importance of external cues to trigger that flow state. It’s not uncommon to find celebrity sports people having such strange habits which look like superstitions. These are hacks to nudge the subconscious into a specific state. What an ignorant observer thinks of as a superstition is a scientifically proven mental trick to put the mind into an optimal state.

So how can mere mortals like us, who probably are never going to compete professionally in sports or any similar activity, benefit from this idea?

Well, if you are reading this, chances are you work in a setup where being good at reading, thinking and decision making are one of the most important traits for being successful. Whether you are an investor, software engineer, or a business executive, to be able to focus and think deeply about problems should be very important for you. Isn’t it?

In short, the most successful people in the modern world are those who can do deep work for extended periods of time. Deep work, according to Cal Newport, author of the book with the same title, is defined as –

Professional activities performed in a state of distraction free concentration that push your cognitive abilities to their limit. These efforts create new value, improve your skill, and are hard to replicate.

But the constant distraction and information overload of the modern work is the biggest enemy of the deep work. Relying only on your willpower to keep away the distractions and bring focus isn’t going to take you far. You need hacks. Like Nadal does. Like Manish did.

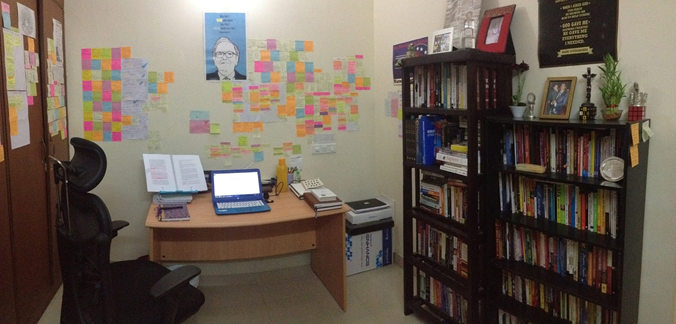
One such hack is to build a magic corner in your home or workplace. If you can afford a separate room or office, nothing like it but getting started with a small corner in your house is perfectly fine. A corner which has lots of visual cues related to the work that you want to learn to become better at. It can have post-it notes with quotes from your people who you want to emulate. You could perhaps have small pictures of them stuck on the wall as a reminder. Post-it notes can have lots of ideas that you find interesting and want to pursue in future.

You could have your bookshelf, reading chair and study table like I have done. See the above a picture of my magic corner at home.

My goal is to become an effective reader and better thinker. And building this magic corner has been the biggest personal discovery for me. This is the place where I spend most of my time reading, thinking, writing, learning, unlearning, imagining, wondering, connecting the dots and even dozing off (to facilitate diffused learning). When you enter the magic corner, its vibrations and energy gets hold of your subconscious and quickly puts you in the zone.

The zone where ideas, insights and creative juices start flowing uninhibited. Your magic corner becomes the pink shirt.

The more time one spends in his magic corner the stronger would be its vibrations and more productive it would become for you. It’s the perfect example of a positive feedback loop working in your favour. Anytime you want to enter your zone, your flow state, all you would need to do is go to your magic corner.

For that matter, a magic corner doesn’t necessarily have to be a physical space. It could be a slice of time in your day. You could carve out 30-40 minutes window of time from your day and reserve that period only for learning purpose. However, it can’t be a moving window. It needs to be a recurring period every day at the same hour. Like magic corner has a fixed place, your ‘magic-time-corner’ needs to be at a fixed place in time. It could be in the early morning, late evening or even during the day but you must mark it fixed. The moment that hour arrives, you must leave what you are doing and resume your creative work.

I have found that a physical magic corner is much easier to implement than a magic-time-corner. You could give a try to both and stick with what works best for you.

I have lost touch with Manish but I am sure by this time he has discovered few more learning and performance hacks. If I meet him again I won’t blow that chance by smirking at his superstitions.

So, what are you waiting for? Arise, awake and get your pink shirt.

[/show_to] [hide_from accesslevel=’almanack-all’]

Want to Read More? This content is exclusive for members of Value Investing Almanack. Login to read if you are a member. Else, click here to subscribe.

Benefits to VIA Members
 
  • Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
  • InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
  • StockTalk: Thorough analysis of business models of companies (without any recommendations)
  • Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
  • BookWorm: Reviews of the best books on Value Investing and related subjects
  • Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
  • Archives: Instant access to our huge archive from the past three years
Become a VIA Member. Click to Subscribe
[/hide_from]

Super Investor: Joel Greenblatt

November 30, 2016

Joel Greenblatt is a very successful value investor and the founder of Gotham Capital. Joel an adjunct professor at the Columbia Business School (Warren Buffett’s alma mater) and author of three investment books namely,You Can Be a Stock Market Genius, The Little Book That Beats the Market and The Big Secret for the Small Investor.

However, the above accolades pale in front of his real accomplishment. His investment firm has averaged a whopping 40% annual return from 1985 to 2016. Just to give you an idea, Rs 100 compounded at the rate of 40% for 20 years turns into Rs 83,600. In the investment world, where 100-baggers are extremely rare events, Greenblatt has turned his investor’s corpus to 800-bagger.

Returns like that don’t come with plain luck. At least not for such a long time. I am sure you are excited to know about the tricks that Joel Greenblatt has up his sleeve that has enabled him to create such an enviable long-term record. You can learn all about his secrets and investing methods in his books but what’s more important to first learn are the basics that underlie his investment process.

<!–more–>[show_to accesslevel=’almanack-all’]

“Without a basic level of knowledge and understanding,” writes Greenblatt, “you can’t tell a great investment from a real dog.” So, before you start implementing the methods, it would be a good idea to reprint the basic principles on your mind’s canvas.

Do Your Own Work

You don’t want to be well paid merely for taking big risks. Anyone can manage that. You want to be well paid because you did your homework…Your extraordinary profits will not be a result of taking on big risks; they will be the justly deserved pay for doing your homework.

In fact, as an investor, your primary task is to reduce risk as much as possible. And the only way to do that is to know what you are getting into, i.e., putting an independent thinking to whatever investments you are making. There is no substitute for hard work, goes the adage. But in investing, it’s not the hard work alone that counts most, it’s the thoughtful-hard-work that generates the best returns.

Today, merely reading all the material available on a company doesn’t give you any special edge. Information is accessible to everyone. What brings an edge to a small investor today is the ability to generate superior insights using the same information which is available to others. Superior insights don’t come from borrowed conviction. They come from sitting in the room alone, revving up your brain’s CPU and connecting the dots.

Most Trusted Advisors aren’t Trustworthy

The odds of anyone calling you on the phone with good investment advice are about the same as winning Lotto without buying a ticket…The vast majority of analysts are directly paid by clients. The research recommendations and reports produced by these analysts are peddled by the firm’s stock brokers in exchange for commission business. One perennial problem is the overwhelming incentive for analysts to issue “Buy” recommendations. The universe of stocks not owned by a customer is always much larger than the list of those currently owned. Consequently, it’s much easier to generate commissions from new “Buy” recommendations than from recommendations to sell.

The incentives of a large part of the financial industry are misaligned with the clients it serves. Most mutual fund and hedge fund managers are more interested in bigger assets under management (AUM) rather than long-term performance. Their incentives are directly proportional to the size of the fund they manage. Similarly, the stock research team owned by most big investment banks don’t want to issue a negative report on a company because they don’t want to lose the chance of getting an investment-banking assignment from the same company in future. For that matter, most personal finance advisors are merely mutual fund agents in the garb experts.

So, the lesson for an investor is that he or she shouldn’t invest based on the stock tips provided by stock brokers and other finance professionals. Always ask, what’s the advisor’s incentive? Where does he or she make money from? And even if you have ensured your advisor is truly independent in dispensing advice, don’t trust him completely. Find out what is his own investment philosophy? Does he invest in the same assets which he is recommending to you?

Pick Your Spots

The most successful horse players are the ones who don’t bet on every race but wager on only those occasions when they have a clear conviction. It makes sense that if you limit your investments to those situations where you are knowledgeable and confident, and only those situations, your success rate will be very high.

Warren Buffett has spoken about the same idea many times. He calls it “sticking to your circle of competence.” To get better returns in equities doesn’t mean that one needs to invest in the hottest sectors. It doesn’t even mean catching the latest trends. When you pick businesses based on your knowledge and understanding of a particular industry, sector or class of businesses, it becomes highly likely that you’ll not make the mistake of investing in a bad business.

The fact that this highly selective process may leave you with only a handful of positions that fit your strict criteria shouldn’t be a problem. The penalty you pay for having a focused portfolio – a slight increase in potential annual volatility – should be far outweighed by your increased long-term returns.

Don’t Buy More Stocks

For many people, especially a small investor, a stock portfolio is only a portion of his entire investment holdings. Most people, reasons Greenblatt, have a portion of their net worth in bank savings, debt funds, real estate and life insurance policies. Which means, their investments are already quite diversified. On top of that, if the investor diversifies his or her stock portfolio in two dozen different stocks, it doesn’t reduce the risk any further, however, it does ensure mediocre returns.

Ideally, your decision to buy and sell stocks should be based solely on the investment merits. This may mean leaving that extra money in the bank or in other assets, even if you’ve made up your mind that socks are the investment vehicle of choice. Leaving some of your assets on the side-lines (i.e., out of stock market) should be your compromise to prudent diversification. As long as you’re willing to do your own homework, a strategy of owning a select handful of your favourite stock situations should yield results far superior to a strategy of owning dozens of different stocks or mutual funds.

Look Down, Not Up

One of the reasons most people look at stock market investing as a risky proposition is that they have an incomplete, if not flawed, view of risk. For most investors, risk is thought of as the risk of receiving volatile returns. On top of that, the distinction between upside volatility and downside volatility is greatly confused.

Moreover, volatility is calculated based on past price movements of a stock which can lead to a faulty conclusion about future performance. The truth, according to Greenblatt, is you can’t really tell much of anything just from measuring a stock’s past price movements. In fact, the riskiest thing about focusing on past price movements is that it doesn’t tell you how much you can lose.

So, one way to create an attractive risk/reward situation is to limit downside risk severely by investing in situations that have a large margin of safety. The upside, while still difficult to quantify, will usually take care of itself. In other words, look down, not up, when making your initial investment decision. If you don’t lose money, most of the remaining alternative are good ones. While this basic concept is simple enough, it would be very difficult to devise a complicated mathematical formula to illustrate the point.

Conclusion

Vince Lombardi is remembered as the greatest coach in American football. At the beginning of every coaching season, he would gather the players around, hold the football in one hand, and say, “Gentlemen, this is a football.” It may sound funny because he wasn’t coaching novices. His players were already accomplished, professional players.

But the story goes that he held up the football as though they had never seen one before. He would describe its importance; he would then take th

e team out and show them the field. He’d point out the rules of the game. Then, he would remind the players the basics of how the game is played.

Lombardi stressed fundamentals. He knew that the secret to extraordinary performance was taking the ordinary aspects of the game i.e., basics and giving them extraordinary focus.

Warren Buffett, even after 65 years of having discovered Benjamin Graham’s book, The Intelligent Investor, considers it as the most important text for every value investor. None of the investing basics that we read above should be new to those who have been learning and practicing value investing for some time. However, it’s important to keep reminding ourselves about the basics.

And that’s because, as I wrote at the beginning, methods change, principles don’t.

[/show_to] [hide_from accesslevel=’almanack-all’]

Want to Read More? This content is exclusive for members of Value Investing Almanack. Login to read if you are a member. Else, click here to subscribe.

Benefits to VIA Members
 
  • Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
  • InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
  • StockTalk: Thorough analysis of business models of companies (without any recommendations)
  • Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
  • BookWorm: Reviews of the best books on Value Investing and related subjects
  • Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
  • Archives: Instant access to our huge archive from the past three years
Become a VIA Member. Click to Subscribe
[/hide_from]

Life 2.0: The Only Scorecard that Matters in Life and Investing

October 30, 2016

Lots of people I know have been victims of harassment and trolling on social media. Over the years, and especially in recent times, I have also been picked on by a few trolls to the point where it became ridiculously easy to predict exactly what they’re going to do on something I post or tweet, and how they are going to blow everything I say out of context, and how they’re going to whine and make a big deal out of things that shouldn’t even be of their concern to begin with.

Earlier I used to respond to these trolls with clarifications and counter-arguments. As I realized, that was useless and disturbing, especially for all others who were also hearing the noise coming out of my home (where these trolls had barged into).

Then I stopped replying to such criticism and kept quiet till people got personal – like someone recently calling me “grossly overrated value homeopathic quack.” 😉 And then I started blocking people sending such stinkers. In fact, I used the blocking tool generously.

Now, I realize even that tool does not serve much purpose. This is because even when I block people sending me negative criticism (and that too personal), I am still giving them and their thoughts some importance.

<!–more–>[show_to accesslevel=’almanack-all’]

This realization set in when I asked a question to a person I respect a lot. My question was – “How do you deal with people who negatively criticize you or your work etc. on social media platforms? I allow for some such criticism and then block people who continue to do it. Is this the right/wrong thing to do?”

He replied, “Block trolls. Allow constructive criticism of ideas. If it gets personal, block.”

Before I could reply, he sent me another email with the message, “And have an inner scorecard. You don’t have to give much weight to what someone unimportant to you thinks of you.”

Inner Scorecard?

This last point – about having an inner scorecard – got me thinking. Interestingly, I had come across this thought just a few days back while reading Warren Buffett’s biography Snowball.

In this book, Buffett is quoted in Chapter 3 as saying…

The big question about how people behave is whether they’ve got an Inner Scorecard or an Outer Scorecard. It helps if you can be satisfied with an Inner Scorecard.

I always pose it this way. I say: ‘Would you rather be the world’s greatest lover, but have everyone think you’re the world’s worst lover? Or would you rather be the world’s worst lover but have everyone think you’re the world’s greatest lover?’ Now, that’s an interesting question.

Here’s another one. If the world couldn’t see your results, would you rather be thought of as the world’s greatest investor but in reality have the world’s worst record? Or be thought of as the world’s worst investor when you were actually the best?

In teaching your kids, I think the lesson they’re learning at a very, very early age is what their parents put the emphasis on. If all the emphasis is on what the world’s going to think about you, forgetting about how you really behave, you’ll wind up with an Outer Scorecard.

Now my dad: He was a hundred percent Inner Scorecard guy. He was really a maverick. But he wasn’t a maverick for the sake of being a maverick. He just didn’t care what other people thought. My dad taught me how life should be lived. I’ve never seen anybody quite like him.

These are special words, and you must read them again. Like I did after receiving the email from the gentleman I admire a lot.

Let’s face it. Not a day goes by that we are not tempted to glance to the left and to the right to see how we measure up to the people around us and what others think of us and our work. But it doesn’t stop there, does it?

We’re tempted to compare our children to other children, our spouse to other spouses, our salary to others’ salaries, our car to others’ cars…and our stocks to others’ stocks. It’s frustrating. It’s exhausting. And as Buffett would tell you, it’s a trap.

This act of comparison with others – or seeking validation from others – is what is driven by living with an Outer Scorecard. And all it leads to is constant frustration, because we will never stand up perfectly to what everyone else wants us to look like or be like. Over that, there are many of those who are waiting to criticize and pull us down, whatever we say or do.

No One Ever Kicks a Dead Dog

When you are kicked and criticized, remember that is often done because it gives the kicker a feeling of importance.

It often means that you are accomplishing something and are worthy of attention. Many people get a sense of savage satisfaction out of denouncing those who are more successful.

Consider this story that Dale Carnegie shared in his book How to Stop Worrying and Start Living of Admiral Robert Peary who…
…startled and thrilled the world by reaching the North Pole with dog sleds in 1909 – a goal that brave men for centuries had suffered and starved and died to attain. Peary himself almost died from cold and starvation; and eight of his toes were frozen so hard they had to be cut off. He was so overwhelmed with disasters that he feared he would go insane. His superior naval officers in Washington were burned up because Peary was getting so much publicity and acclaim. So they accused him of collecting money for scientific expeditions and then “lying around and loafing in the Arctic”. And they probably believed it, because it is almost impossible not to believe what you want to believe. Their determination to humiliate and block Peary was so violent that only a direct order from President McKinley enabled Peary to continue his career in the Arctic.

So if someone like Admiral Peary who achieved something amazing and praise worthy can still be criticized/trolled, perhaps his story can give us comfort the next time we’re attacked by unjust criticism.

As long as in your heart you know you did the right thing or you believe in what you did, unjust criticism should be considered and analyzed whether it truly has any merit, but not be given permission to belittle what you are trying to achieve.

Also remember what Carnegie wrote in his book…

“…unjust criticism is often a disguised compliment. The more important a dog is, the more satisfaction people get in kicking him.”

Inner Scorecard and Investing

The concept of Inner Scorecard isn’t restricted to how you live your life alone, but also follows through to how you invest your money.

Howard Marks wrote this in Chapter 10 of The Most Important Thing…

…thoughtful investors can toil in obscurity, achieving solid gains in the good years and losing less than others in the bad. They avoid sharing in the riskiest behavior because they’re so aware of how much they don’t know and because they have their egos in check. This, in my opinion, is the greatest formula for long-term wealth creation – but it doesn’t provide much ego gratification in the short-term. It’s just not that glamorous to follow a path that emphasizes humility, prudence, and risk control. Of course, investing shouldn’t be about glamour, but often it is.

And then, remember what Ben Graham wrote in The Intelligent Investor?

You are neither right nor wrong because the crowd disagrees with you. You are right because your data and reasoning are right.

…and that’s the only thing that makes you right. Then, you don’t have to worry about anybody else.

And then, like Buffett is quoted in Snowball, if your investment results are not there in front of others to see (and this is one grouse a few trolls have with me – they don’t get to see my investment results and thus question it despite I never making much fuss about it), you are better off being thought of as the world’s worst investor when you know that you are doing sufficiently well for yourself.

Conclusion

Thriving in the real world requires the mindset of working with an Inner Scorecard. Not a religious devotion, but a commitment to the work, as opposed to the rewards.

Even if we do everything right, the reaction might be failure, disrespect, jealousy, or even a resounding yawn from the world. If we are motivated by the wrong thing – if ego holds sway – this response will crush us.

I’ve seen it happen a hundred times. I’ve done it myself too. And, yet, far too many of us only feel strong enough to pursue our dreams when we have a team of people cheerleading in the background. That’s having an Outer Scorecard and the problem is obvious.

If you live based on your Outer Scorecard, you fall to pieces when people stop cheering. It’s a brave soul – one with the Inner Scorecard – who can keep moving when all seems lost, all the fans have left the building and, in their place, are people shooting, “Boo!”
The world is, after all, indifferent to what we humans want. What can go wrong will. Only misery and disappointment awaits. But if we can find joy and satisfaction in the work, that can be ours right now.

The biggest lesson of living with an Inner Scorecard is that you must not aim to be the best out there. Rather, you must aim to be the ‘best you’ you can become. And in that pursuit, anyone who sends you his or her unjust or negative criticism, or trolls you, has no space or identity. You must ignore such people completely and, like I have done now, unblock them in case you blocked them earlier. 🙂

Let them say whatever they have to say about you, for you are now working with an Inner Scorecard, not Outer.

[/show_to] [hide_from accesslevel=’almanack-all’]

Want to Read More? This content is exclusive for members of Value Investing Almanack. Login to read if you are a member. Else, click here to subscribe.

Benefits to VIA Members
 
  • Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
  • InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
  • StockTalk: Thorough analysis of business models of companies (without any recommendations)
  • Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
  • BookWorm: Reviews of the best books on Value Investing and related subjects
  • Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
  • Archives: Instant access to our huge archive from the past three years
Become a VIA Member. Click to Subscribe
[/hide_from

  • « Go to Previous Page
  • Page 1
  • Interim pages omitted …
  • Page 8
  • Page 9
  • Page 10
  • Page 11
  • Page 12
  • Interim pages omitted …
  • Page 20
  • Go to Next Page »

Handcrafted with in India