
Valuing stocks seems like a tough task in itself and more difficult is drawing a line between paying up and overpaying. Here are some insights on this topic I draw from investing legends and their experience.
Charlie Munger said this in his landmark speech titled – A Lesson on Elementary, Worldly Wisdom As It Relates To Investment Management & Business…
Over the long term, it’s hard for a stock to earn a much better return than the business which underlies it earns. If the business earns 6% on capital over 40 years and you hold it for that 40 years, you’re not going to make much different than a 6% return—even if you originally buy it at a huge discount.
Conversely, if a business earns 18% on capital over 20 or 30 years, even if you pay an expensive looking price, you’ll end up with a fine result.
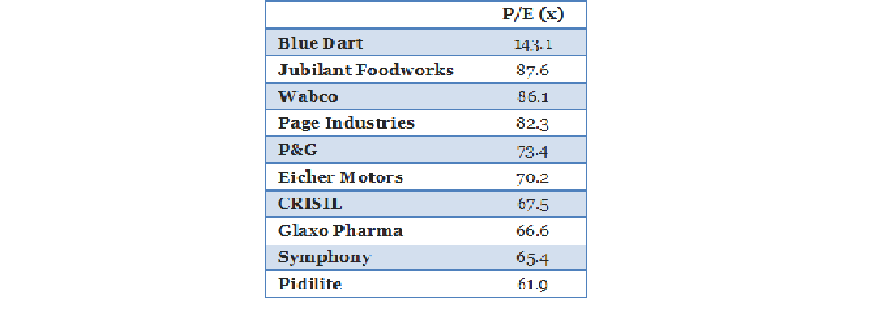
Now, if I were to look at some of the high quality businesses in India, it surely seems that investors are taking Mr. Munger’s idea about paying an “expensive looking price” very seriously. Here are, for instance, the P/E ratios of some high quality businesses…
In Lewis Carroll’s “Through the Looking Glass”, Alice’s finds that she has to run faster and faster just to stay in place.
Well, in our country,” said Alice, still panting a little, “you’d generally get to somewhere else if you run very fast for a long time, as we’ve been doing.
Here’s the advice Red Queen, an antagonist in the story, offers Alice…
A slow sort of country!” said the Queen. “Now, here, you see, it takes all the running you can do, to keep in the same place. If you want to get somewhere else, you must run at least twice as fast as that!
In sum, the Red Queen advises Alice to exert ever more effort just to maintain her current position.
Evolutionary biologist Leigh Van Valen took inspiration from the Red Queen’s words and proposed a principle called the Red Queen Effect in 1973 to explain how, for an evolutionary system, continuing development is needed just in order to maintain its fitness relative to the systems it is co-evolving with.
In biology, this means that animals and plants don’t just disappear because of bad luck in a static and unchanging environment, like a gambler losing it all to a run of bad luck at the casino.
Instead, they face constant change – a deteriorating environment and more successful competitors and predators – that requires them to continually adapt and evolve new species just to survive.
This theory has been applied to explain the relatively high speeds of rabbits and foxes, each of which developed faster running abilities in an attempt to gain respective advantage in the predator-prey relationship between these two animals.
[show_to accesslevel=’almanack-all’]
————————Art of Investing Workshop in Pune————————
After having covered 300+ participants over the last two years, Safal Niveshak’s Art of Investing Workshop travels to Pune on 27th October 2013. If you wish to get set on the path of transforming your relationship and results with your money, , click here to register now !
————————————————————————————————————————–
Red Queen Effect in Business
In the business world, the Red Queen Effect is in place where there are two emerging strong competitors who, by trying to stay ahead of the other, keep improving their products/services at a pace that effectively drives the remaining competitors out of the market or to the brink of irrelevance.
Like in an evolutionary system, the Red Queen Effect helps continuing development in business by pushing companies to maintain their fitness relative to the systems they are co-evolving with.
However, in a large number of instances, the Red Queen Effect leads to death of companies that either cannot keep pace with the rate of change around them, or are adamant to use their success tactics of the past to survive in the changing times.
Here’s how it happens…

Here’s the paradox – the more aggressively a firm competes, the greater its performance. But by competing so aggressively, it also forces its rivals to compete more aggressively, thus improving their performance.
By being competitive and thus successful, a firm also creates more competitive and thus more successful rivals for itself.
In the book The Global Brain, the authors describe the Red Queen Effect in terms of its impact on business as…
Despite having hundreds of in-house scientists and engineers working tirelessly on innovation projects…innovation pipelines are not delivering the results they need to sustain growth. Innovation productivity is declining while the cost of new product development is increasing day by day. Investing more dollars into internal R&D efforts does not seem to produce the desired payoffs.
Look at pharma R&D, or technology R&D…and you will see the Red Queen Effect widely prevalent…and that’s why it’s so difficult to foresee any clear future for these companies.
Who would have predicted the fall of Nokia a few years back? How many can think of a similar fate for Apple or Google 20 years down the line?
It explains why Buffett and several other value investors have largely stayed away from technology stocks for so many years, despite others making money off it.
Another negative side of the Red Queen Effect is that, in their efforts to beat the competition, a lot of companies tend to overdo things. So, a company would…
Acquire left, right, and centre…just because the CEO wants to grow his company larger before he retires, or because the competitor is doing so.
Spend aggressively on capacity building to fuel growth, while not keeping a eye on the balance sheet.
Take up unprofitable projects to grow volumes faster than the industry, while ignoring that new projects are consuming more cash than they are earning.
Grow the employee base to grow revenues (IT services companies)
Red Queen’s Slaying Demon – Inflation
Warren Buffett wrote this in his 1980 letter to shareholders…
Unfortunately, earnings reported in corporate financial statements are no longer the dominant variable that determines whether there are any real earnings for you, the owner. For only gains in purchasing power represent real earnings on investment.
If you (a) forego ten hamburgers to purchase an investment; (b) receive dividends which, after tax, buy two hamburgers; and (c) receive, upon sale of your holdings, after‐tax proceeds that will buy eight hamburgers, then (d) you have had no real income from your investment, no matter how much it appreciated in dollars. You may feel richer, but you won’t eat richer.
High rates of inflation create a tax on capital that makes much corporate investment unwise – at least if measured by the criterion of a positive real investment return to owners. This “hurdle rate” the return on equity that must be achieved by a corporation in order to produce any real return for its individual owners ‐ has increased dramatically in recent years.
The average tax‐paying investor is now running up a down escalator whose pace has accelerated to the point where his upward progress is nil.
In a world of 15% ‘actual’ inflation, where a business consistently earning 20% return on equity (which is rare) and distributing it all to individuals in the 30% bracket is eating up their real capital, not enhancing it.
After 30% of 20%, or 6%, goes to the income tax department, the remaining 14% leaves investors 1% down (14% post-tax return minus 15% inflation) in real purchasing power as compared to the start of the year.
I repeat – a business earning a consistent 20% return on equity, while not employing a high debt, is rare.
Look at your portfolio, and if you find businesses that are consistently earning less than 20% return on equity, know that they are actually killing your wealth in a world of 15% inflation and 30% income tax. Like some of these businesses…

If you own such businesses, you are very much like this woman who tries to walk up a down escalator…
In order to beat inflation over the long run, you need to own businesses that keep earning you 20%+ return on equity (what the Red Queen prescribed), and at the same time, aren’t playing around with their balance sheets to create artificially high returns.
One important point to note here is that you must not be blind to a business that is earning a high return on equity, say in excess of 30-40% (like Infosys or TCS).
As I mentioned in the first chart above, such a business’s competitors (existing and potential) won’t sit quiet, and would instead work hard to make incremental improvements in their business models, thus leading to an “arms race” within the industry.
Then, if such companies respond to the changing times with success strategies that worked in the past, they may pay the price in the form of lower economic profits, and return on equity, thus eventually falling to the Red Queen Effect.
So, what should you do?
Buy businesses that earn high return on equity consistently while keeping their borrowings low, but keep a watch on them and their competitors.
Keep a watch on the money the company is spending on capex and/or incremental working capital, and question the logic behind such expenditure.
If such new expenditure (on capex and/or working capital) doesn’t increase the company’s volumes and/or market share, it’s usually a warning signal of times to come.
Beware of Gruesome Businesses
In a brilliant post in 2012, Prof. Sanjay Bakshi explained the Red Queen Effect on companies that have to…
Continue adding to their capital base to grow their businesses,
Take up more and more borrowings to fund such an expansion, but still. Earn weak economic earnings / free cash flows.
Such companies are Warren Buffett’s “gruesome” businesses you must avoid at all cost.
Here is what Buffett wrote in his 2007 letter…
The worst sort of business is one that grows rapidly, requires significant capital to engender the growth, and then earns little or no money. Think airlines. Here a durable competitive advantage has proven elusive ever since the days of the Wright Brothers.
Most asset-heavy or commodity businesses would fall into this category. As Buffett wrote in 1983…
…as they generally earn low rates of return – rates that often barely provide enough capital to fund the inflationary needs of the existing business, with nothing left over for real growth, for distribution to owners, or for acquisition of new businesses.
Red Queen and the Business of Life
Often, the Red Queen thinking is a learned behaviour – companies “learn” to behave in a specific ways from their competitors, even those with who they don’t share a co-evolutionary history.
This is also true of the rat race most of us are running in our lives.
I will get jealous seeing my neighbour buying a luxury car, and will end up copying him only to realize later that I did not have the financial capacity to have done that.
I also realize later that my neighbour bought his car to show-off in the society, but for which he had to indulge in a large bank borrowing.
So, we both end up destroying our financial lives, trying to play the game of one-upmanship…trying to keep pace with each other’s indulgences.
I have known so many people who are walking up a down escalator – buying bigger houses, cars, and habits than they can afford, then loading up on bank borrowings, and then spending their life’s precious years working for their banks and not for themselves or their families.
If you remember, the Red Queen is the one who runs hard but never gets anywhere because everything else in the landscape is also running. And as she tells Alice, “It takes all the running you can do to keep in place!”
So my question to you is – Do you see the Red Queen Effect affecting your life and investment portfolio? If yes, what are you doing to remove it?
Afterthought
Akhilesh, a dear friend and tribesman, has shared a story of a Brazilian ex-billionaire Eike Batista who is one step closer to bankruptcy after missing a US$ 45 million debt payment that was due early this month. If his company goes under, its large US creditors stand to lose millions in Latin America’s largest corporate default.
Batista’s fault? He has been a CEO with an overgrown ego, which has cause outsized problems for his company and investors. All of his misdoings can be explained by the Red Queen Effect, as you can read here.
Also Read
- The Final Relaxo Lecture ~ Prof. Sanjay Bakshi
- Value Investing, the Sanjay Bakshi Way 2.0 – Part 1
- A Lesson on Elementary, Worldly Wisdom As It Relates To Investment Management & Business ~ Charlie Munger
- Pay Up, But Don’t Overpay ~ Sanjay Bakshi

- Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
- InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
- StockTalk: Thorough analysis of business models of companies (without any recommendations)
- Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
- BookWorm: Reviews of the best books on Value Investing and related subjects
- Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
- Archives: Instant access to our huge archive from the past three years