
In his 2010 letter to shareholders, Warren Buffett tells a joke —
Customer: Thanks for putting me in XYZ stock at 5. I hear it’s up to 18.
Broker: Yes, and that’s just the beginning. In fact, the company is doing so well now, that it’s an even better buy at 18 than it was when you made your purchase.
Customer: Damn, I knew I should have waited.
Reading this joke the first time, I laughed at broker’s convoluted argument and the stupidity of the customer. How can a stock be better buy at 18 than it was at 5?
[show_to accesslevel=’almanack-all’]
It looked that the broker was simply trying to find baseless reasons to make his customer buy more. After all, a broker’s primary incentive is to make his clients transact more, isn’t it?
Add to that the customer’s naive observation. He had bought XYZ stock at 5 which was now trading at 18. Why on earth should he have waited?
It took me few years of reading and investing to conclude that broker’s claim was very much a real possibility. In fact, it’s not even an exception. It’s almost like a rule in value investing when it comes to finding long term mega-compounders.
The first clue comes from the famous British economist John Maynard Keynes. He said –
When the facts change, I change my mind. What do you do, sir?
How can change in facts make a stock more attractive at 18 than it was at 5? I think you would’ve guessed by now. But let me say it anyway.
When you buy a company at 5 whose intrinsic value is 10, you’re buying a dollar for 50 cents. Pretty good deal. But what if the company continues to increase its intrinsic value rapidly and the price doesn’t catch up as fast, then it’s possible that the same company is available at 18 where the intrinsic value has vaulted to 50. Now you’re getting the same stock at 74 percent discount. Isn’t it a better deal than it was previously?
When the facts change, a good stock can become a great stock even at a higher price. Remember Warren Buffett’s statement on the relationship between time and the quality of businesses? He said —
Time is friend of a wonderful business and an enemy of a terrible one.
So the broker might have been right. Perhaps the XYZ stock increased its intrinsic value so much that it became a more compelling buy at a higher price than it was earlier at a lower price.
Now I’ll come to the customer’s observation that he should have waited. No, he shouldn’t have waited. In fact, if he knew that company was going to be a better buy at 18, he would’ve bought more at 5. Since he didn’t, at least now he had another opportunity to accumulate more.
Unfortunately, it’s easier said than done.
This is where the behavioural aspects of investing come in. For most investors, including yours truly, it’s maddeningly hard to buy a stock from the current portfolio at higher price. Averaging up is harder than averaging down.
If I was evenly split between two equally attractive stocks, I would prefer the one which I don’t hold in my portfolio currently. In other words, I would rather choose to explore a new opportunity rather than exploiting an existing one. This bias — the tendency to get anchored to the first purchase price — makes you blind towards the stocks that you already own.
The customer (in the joke) perhaps was very intelligent and understood this bias. That’s why he wondered if he should have waited. It would have been much easier for him to buy the same stock starting from scratch than to accumulate it further.
When you accumulate an existing stock, you’re in a way exploiting an opportunity. Deciding to add a new stock in the portfolio is akin to exploration. Exploration at the cost of exploitation.
Which means an investor has to strike the right balance between exploration and exploitation.
Let’s bring in the ants now.
Scientists have always suspected that there isn’t a single human problem today that hasn’t already been tackled and solved by mother nature in some way.
A lot of scientific breakthroughs in mapping the human behaviour have come from extensive study of animal kingdom. Rats, pigeons and ants are the favourite of scientists.
The puzzle of how ants find food has baffled the scientists for decades. In spite of several competing theories, none have been able to explain this riddle satisfactorily. The jury is still out on what search algorithm ants use for finding food efficiently.
Nevertheless, in the process of observing these tiny creatures scurrying around, Myrmecologist (scientists who study ants) decoded many other patterns resulting in useful insights for solving real world problems like traffic movement and investment strategies.
Drawing insights from the foraging behaviour of ants, Michael Mauboussin, in his book More Than You Know, writes —
Foraging ants depart the nest with one job in mind, to find and retrieve food. They also have the ability to leave and follow chemical trails. At first, they disperse randomly. When the ants that find food come back to the nest, they leave a chemical trail that their sisters can follow. Studies show that this process allows ants to consistently find the shortest path to the food.
Once researchers understood this collective ability, they decided to play a trick on the ants. In a controlled setting, the scientists placed two food sources at identical path lengths from the nest. As it turned out, the ants ended up using just one of the paths, although they chose at random. Why? Because they follow chemical trails, a couple more ants going down one path will attract other ants, triggering a positive feedback loop. So instead of finding an optimal solution, the ants have one crowded path and an equally long empty path.
Amazingly, though, nature anticipated this problem as well. As it turns out, ants periodically break from the main path and begin a random search process again. The ants are “programmed” to strike a balance between exploiting a known food source and exploring for the next food source (see the image below). Johnson calls this the “wild hair” alternative. The ants are hard-wired to seek diversity.
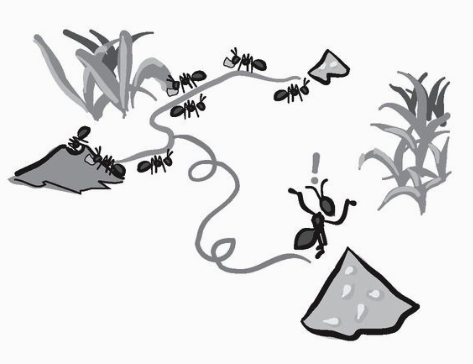
Most ants erred on the side of exploitation of existing food source rather than continuing their exploration. This ant-strategy has useful lessons for the investors.
As a software developer, writes Moxie Marlinspike, an American computer security researcher, “I envy writers, musicians, and filmmakers. Unlike software, when they create something it is really done, forever.”
True for investing too. You can never say that you’re done investing in a particular stock. By buying it, you’ve just explored it. Have you exploited it completely?
In November 2009, Warren Buffett purchased 77 percent of Burlington National Santa Fe (BNSF) — a private railway company — for $24 Billion. This purchase made BNSF a fully owned subsidiary of Berkshire because they already owned 23 percent of BNSF prior to this deal. And like everytime, Buffett had a joke for this occasion too. He said,
This is all happening because my father didn’t buy me a train set as a kid.
Since that transaction, BNSF has generated a cumulative profit after taxes of $28 Billion between 2010 and 2017. A $24 Billion investment that paid for itself in just 9 years. And decades of useful life is still ahead of it.
BNSF wasn’t the only stock where Buffett realized that something in his portfolio had become a better buy at a higher price. In fact, the customer-broker joke was mentioned by him in the context of another such deal — GEICO. Buffett wrote —
Berkshire acquired GEICO in two stages. In 1976-80 we bought about one-third of the company’s stock for $47 million. Over the years, large repurchases by the company of its own shares caused our position to grow to about 50% without our having bought any more shares. Then, on January 2, 1996, we acquired the remaining 50% of GEICO for $2.3 billion in cash, about 50 times the cost of our original purchase.
What I learn from ants and from Buffett’s GEICO and BNSF deals is that you shouldn’t ignore your existing portfolio as an important place for finding new investment opportunity. As time passes a great stock keeps getting better and you need to exploit it by buying it even more.
Moreover, this approach gives you an opportunity to evaluate your current holding and discover if the facts have changed for the better. Like it happened in case of Eicher Motors.
In 2008, Professor Sanjay Bakshi bought Eicher Motors as part of a special situation (arbitrage) transaction. In his note on that deal, Prof. Bakshi writes —
At Rs 126 effective cost to us, Eicher Motors will be a ridiculously low-priced bargain stock. Post buyback, the company will have 24.4 million shares. At that cost price, we will end up buying at a total company value of $64 million. What do we get in return for this investment? We get a debt-free business at Rs 126 per share in possession of the following assets: (1) cash of approximately $75 million (Rs 147 per share); (2) ownership stake in a JV valued at $417 million; and (3) a motorcycle business (minor).
Any investor who would have bought Eicher in 2008, it would have been for the cash bargain and for the equity in the Eicher-Volvo JV. Eicher’s motorcycle business was too small to be given any importance at that time.
However, as the facts changed quickly, i.e., Eicher’s motorcycle business grew and started eclipsing everything else, for an investor who already owned Eicher, exploiting this emerging opportunity was more sensible than nosing around for a new stock ideas. In this case, exploitation triumphed exploration.
Exploitation vs exploration is a great mental model to de-bias an investor from his prejudices against his current holdings as new opportunity to invest incremental capital.
With recent correction in the markets, it’s probably a good time to review your portfolio and evaluate if any of the existing stocks have become a better buy than they were when you bought them.[/show_to] [hide_from accesslevel=’almanack-all’]
- Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
- InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
- StockTalk: Thorough analysis of business models of companies (without any recommendations)
- Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
- BookWorm: Reviews of the best books on Value Investing and related subjects
- Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
- Archives: Instant access to our huge archive from the past three years