The environment we live in today is pretty complex. No moment is exactly the same. History, as they say, never repeats itself. You can never claim confidently that a set of causes will always replicate the same set of effects unless you’re dealing with hard physical laws.
Even if you do something with good intentions, the inherent complexity of the world will tend to produce results which you could never have anticipated. The world is complex and unfair. Here’s an anecdote to prove my point.
During the British government in India, the city of Delhi was facing the problem of too many venomous cobra snakes. To deal with the issue, government officials offered a bounty for every dead cobra. Initially this was a successful strategy as large numbers of snakes were killed for the reward. Eventually, however, enterprising people began to breed cobras for the income. When the government became aware of this, the reward program was scrapped, causing the cobra breeders to set the now-worthless snakes free. As a result, the wild cobra population further increased. The apparent solution for the problem made the situation even worse.
<!–more–>[show_to accesslevel=’almanack-all’]
Samuel Johnson aptly said, “The road to hell is paved with good intentions.” This story about cobras could be apocryphal, but it brings forth a very important learning about how the world around us works and responds to our actions. It tells us that every action has consequences, intended and unintended. Which means no matter how carefully we plan, we can’t anticipate everything.
This phenomenon is also known as the law of unintended consequences. In simpler words, the law states that sometimes in an attempt to solve one problem, we end up manufacturing another one, perhaps even a bigger than the original problem.
Charlie Munger understood the risks of unintended consequences while dealing with social systems. When asked about corporate responsibility for social problems, he answered –
I’m all for fixing social problems. I’m all for being generous to the less fortunate. And I’m all for doing things where, based on slight preponderance of the evidence, you guess that it’s likely to do more good than harm…What I’m against is being very confident and feeling that you know, for sure, that your particular intervention will do more good than harm given that you’re dealing with highly complex systems wherein everything is interacting with everything else.
The complexity and unpredictability that infects the world around us, pervades through the world of investing too. An investment approach may work for a while, writes Howard Marks, “but eventually the action it calls for will change the environment, meaning a new approach is needed. And if others emulate an approach, that will blunt its effectiveness.”
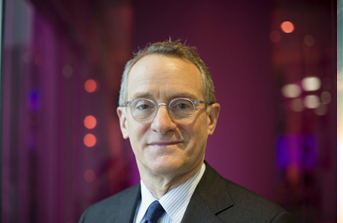
Just in case you haven’t heard of Howard Marks, let me tell you who he is so that you realize how important his words are. Howard Marks manages US$ 90 billion hedge fund called Oaktree Capital and has more than four decades of investing experience. And this what Warren Buffett says about the memos that Marks regularly writes to his clients –
When I see memos from Howard Marks in my mail, they’re the first thing I open and read. I always learn something, and that goes double for his book.
So today we are going to pick Howard Marks’ brains on dealing with this problem of unintended consequence. He recommends something called second level thinking. What’s second level thinking?
If you were thinking like government officials announcing the reward scheme for killing the cobras, you indulged in something called first level thinking. Most people practice first-level thinking. First-level thinkers tend to favour the most obvious and straight answer to a problem. This kind of linear thinking is simplistic and superficial.
If you want to detect signs of first level thinking in your own mind, just ask WHY a couple of times and dig deeper. In most cases, the reasoning led by first-level thinking turns out to be more of an opinion rather than a well thought argument.
However, if one could reason beforehand that, among many other possibilities, one possible outcome of rewarding people for killing cobras is triggering of perverse incentives resulting in cobra-breeding, he or she would be called a second level thinker.
Marks writes –
Remember, your goal in investing isn’t to earn average returns; you want to do better than average. Thus, your thinking has to be better than that of others – both more powerful and at a higher level. Since other investors may be smart, well-informed and highly computerized, you must find an edge they don’t have. You must think of something they haven’t thought of, see things they miss or bring insight they don’t possess. You have to react differently and behave differently. In short, being right may be a necessary condition for investment success, but it won’t be sufficient. You must be more right than others…which by definition means your thinking has to be different.
Gone are the days when access to important information was a privilege. In fact, it would be naive to think that you know more than others just because you have read a company’s annual report and few related articles on the internet. Information technology and internet has democratized the access to information. Any and perhaps all kinds of information is just a click away or rather a touch away, if you have a smartphone. That’s a great advancement but the paradox is, since everyone has access to it, information doesn’t create edge anymore.
Today, the real edge comes from deriving superior insights based on the same facts that everyone has. Edge comes by looking at same things but thinking different thoughts. Edge comes from second level thinking.
Remember what the veteran value investor (the anonymous investor having three decades of experience), who we interviewed in last issue of Almanack, said? Let me pull out his words from VIA archives. He said –
The idea that through numbers and through models you can capture the entire reality is not true. In investing it’s through judgement…If you want to become a better investor, what you really got to focus on is this ability to sharpen your mind in terms of how it processes information…the quality of information is not relevant beyond a point. You’ve got to have what you need to really understand better. Quality is how much it allows you to improve your understanding and interpretation of what you know so that you can translate your interpretation into better judgment which leads to superior behaviour. Because information first needs to be interpreted. That’s the first stage. And understood. So if you can interpret information better than other people, you have an advantage there itself.
Notice the words that I have highlighted in bold above. What those words are saying, repeatedly, is that beyond a point quantity and quality of information ceases to matter. And that threshold point of information is easily available to everyone today. What matters more is the depth and quality of inferences drawn from the public data. The ability to generate superior insights is what separates men from the boys in stock market investing. And second level thinking is the stepping stone for finding superior insights.
Here are a few concrete examples about how second level thinking works in investing, straight from Marks –
First-level thinking says, “It’s a good company; let’s buy the stock.” Second-level thinking says, “It’s a good company, but everyone thinks it’s a great company, and it’s not. So the stock’s overrated and overpriced; let’s sell.”
First-level thinking says, “The outlook calls for low growth and rising inflation. Let’s dump our stocks.” Second-level thinking says, “The outlook stinks, but everyone else is selling in panic. Buy!”
First-level thinking says, “I think the company’s earnings will fall; sell.” Second-level thinking says, “I think the company’s earnings will fall less than people expect, and the pleasant surprise will lift the stock; buy.
Second-level thinking requires you to account for multiple factors. You have to look at a problem from different vantage points. In fact, the foundation of second-level thinking rests more on asking intelligent questions rather finding right answers. For example –
• What is the range of likely future outcomes? (Requires imagination)
• Which outcome do I think will occur? (Requires knowledge and experience about the domain; Requires knowledge of probability and statistics)
• What is the probability that I’m right? (Requires you to be brutally honest about your skills)
• How does my expectation differ from consensus? (Requires knowledge of human behaviour and crowd psychology)
• How does the current price for the asset comport with the consensus view of the future, and with mine? (Requires knowledge of business analysis)
• Is the consensus psychology that’s incorporated in the price too bullish or bearish?
• What will happen to the asset’s price if the consensus turns out to be right, and what if I’m right? (Understanding the risk and the size of potential reward; Ability to handle uncertainty)
For that matter, Porter’s five force analysis model is another great tool to trigger second-level thinking in business analysis. It zooms out your vision to look at the industry and takes your focus away from overly simplistic parameters like P/E ratios.
Second-level thinking is deep, complex, convoluted and pretty heavy duty. Isn’t it? Well, beating the average stock market returns is not easy. And it’s not supposed to be easy, says Munger, “Anyone who finds it easy is stupid.”
First-level thinkers, by definition, can never outperform the market on a consistent basis. Marks argues –
First-level thinkers think the same way other first level thinkers do about the same things, and they generally reach the same conclusions. By definition, this can’t be the route to superior results. All investors can’t beat the market since, collectively, they are the market.
Conclusion
If someone argues that he bought the stock because he had a good experience with the product, you know you are not talking to a second-level thinker.
Generating satisfactory investment returns i.e., at par with broader market, isn’t too complicated. It’s as simple as buying an index fund.
However, the moment people extrapolate this simplicity along with expectation for market beating returns, they forget Albert Einstein’s advice who said –
“Everything should be made as simple as possible, but not simpler.”
I’ll leave you with this final thought from Marks –
“Those who consider the investment process simple generally aren’t aware of the need for – or even the existence of – second level thinking. Thus, many people are misled into believing that everyone can be a successful investor.
Not everyone can. But the good news is that the prevalence of first-level thinkers increases the returns available to second-level thinkers.”
Unlike Olympics, thinking is one skill where your eyes should always be set on the second level than first.
[/show_to] [hide_from accesslevel=’almanack-all’]- Spotlight: Big ideas from Value Investing and why applying them in your investment decision making will be a great deal
- InvestorInsights: Interviews with experienced value investors, learners, and deep thinkers
- StockTalk: Thorough analysis of business models of companies (without any recommendations)
- Behaviouronomics: Deep analysis of human behaviour and how it impacts investment decision making
- BookWorm: Reviews of the best books on Value Investing and related subjects
- Free Course – Financial Statement Analysis for Smart People (otherwise priced at Rs 5,900)
- Archives: Instant access to our huge archive from the past three years